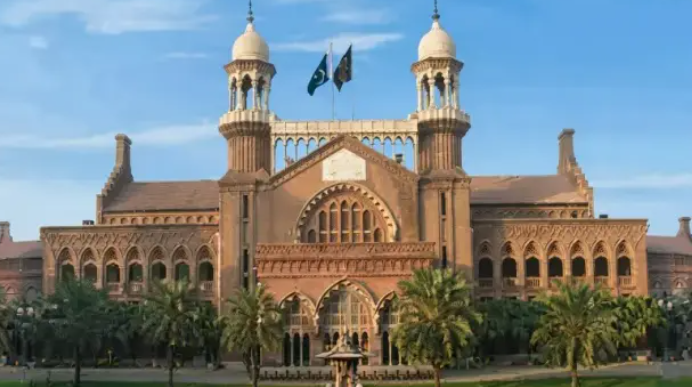
A division bench of the Lahore High Court (LHC), comprising Justice Mirza Viqas Rauf and Justice Anwaar Hussain, has ruled that merely uploading an order to the IRIS tax portal does not constitute valid legal service unless the procedure prescribed by law is followed.
The bench announced its decision while hearing three connected reference applications led by Tahir Mehmood. The petitions challenged orders issued by the Appellate Tribunal Inland Revenue, which had dismissed taxpayers’ appeals as time-barred on the grounds that uploading the relevant decisions to IRIS amounted to sufficient service.
In one of the cases, the taxpayer maintained that the Covid-19 pandemic and mandatory quarantine after returning from abroad had prevented him from accessing the online portal. In the other two matters, taxpayers said they became aware of the Commissioner (Appeals)’ decisions only after receiving recovery notices in April 2026, several months after the orders had been issued.
Writing the judgement, Justice Anwaar Hussain observed that Section 218(1)(d) of the Income Tax Ordinance recognises electronic service only when it is carried out in the manner prescribed by law.
He explained that Rule 74 of the Income Tax Rules defines an electronic address as a fax number or email address and requires confirmation that the communication has been transmitted.
The judge noted that IRIS is an internal, web-based system used for tax administration. Simply placing an order in a taxpayer’s account does not prove that it was transmitted to an electronic address in accordance with the requirements of the relevant rule.
Distinguishing between access to information and formal legal service, the court observed that an order may be available for viewing without having been legally served. It further held that the limitation period for filing an appeal cannot begin on the basis of an event that is not recognised by law as valid service.
The bench also rejected the tax department’s argument that Rule 74 could not impose conditions on the parent legal provision. Justice Anwaar Hussain observed that the requirement to serve notices and orders in the “prescribed manner” was already incorporated into the ordinance.
The court further dismissed the argument that taxpayers were responsible for regularly checking their IRIS accounts to remain informed about official orders.
Addressing the taxpayer’s explanation concerning pandemic-related restrictions, the judge said the tribunal’s decision involved a question of law that the high court was competent to examine.
Emphasising the role of technology in public administration, the judgement stated that digital systems are tools for implementing the law and cannot independently create legal authority or override statutory safeguards.
The bench also referred to relevant judgements delivered by the Peshawar and Islamabad high courts, as well as the Delhi High Court, alongside Articles 4 and 10A of the Constitution.
Ultimately, the LHC set aside the challenged tribunal orders and directed the Appellate Tribunal Inland Revenue to reconsider the taxpayers’ appeals and decide them on merit.